Kroger's Acquisition of Giant Eagle: A Wise Return or Asking for Trouble?
Kroger announced the acquisition of Giant Eagle for $1.65 billion, seen as a return to its M&A strategy. However, analysts point out that this deal is less impressive than previous cases in terms of geographic coverage and asset complementarity, with integration difficulties and competitive pressures coexisting, and the market response has been relatively subdued.
Over the past decade or so, Kroger has largely strayed from the acquisition strategy that fueled its growth. Instead of expanding its footprint and bolstering its assets through regional chain acquisitions, the retail giant focused on tuck-in deals (such as acquiring Home Chef and Murray's Cheese), a lackluster e-commerce partnership, and an overly ambitious merger with Albertsons that ultimately fell through.
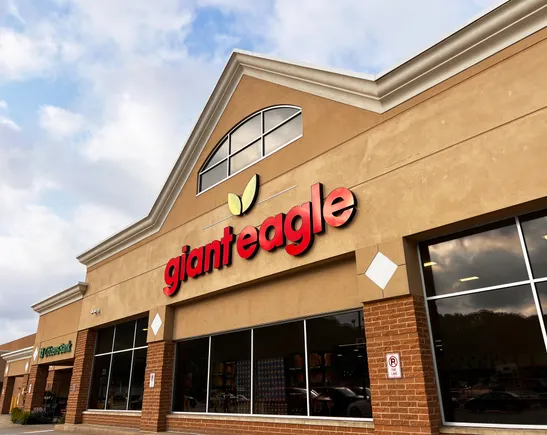
As a result, Kroger's plan to acquire Giant Eagle looks like a return to its traditional playbook. The $1.65 billion deal, expected to close next year, would bring nearly 200 stores and several pharmacies to Kroger. Its price is so low that it's hard to refuse, much like a well-orchestrated in-store promotion.
Analysts at R5 Capital Markets wrote in a research note on Wednesday that the acquisition amount is roughly equivalent to four days of Kroger's total business sales—"a drop in the bucket considering Giant Eagle's estimated revenue of about $9 billion."
But is Kroger getting good value for its money? In my view, the benefits seem rather mixed.
Looking back, Kroger's acquisitions either helped it enter new regions or brought valuable assets. The 1998 acquisition of Fred Meyer allowed it to expand into the western U.S. market; the 2014 acquisition of Harris Teeter gave Kroger a then-advanced e-commerce platform that proved instrumental in refining and building its online grocery business.
The geographic benefits of adding Giant Eagle are obvious, but they seem less compelling than those of past deals. Kroger already has stores in four of the five states where Giant Eagle operates. The main market gains are in Pennsylvania—where Kroger currently has no stores, especially western Pennsylvania where Giant Eagle has built a strong presence from its Pittsburgh headquarters—and in northeastern Ohio, a market Kroger exited decades ago.
At the same time, I'm not sure Giant Eagle possesses unique advantages that Kroger lacks. The two grocers are genetically similar: both have deep investments in pharmacy, private labels, and retail media, and both operate upscale supermarket formats—Giant Eagle's Market District and Kroger's Marketplace stores. These assets may integrate smoothly with Kroger's existing operations, but they seem to lack a true standout like Harris Teeter's online business or Mariano's foodservice expertise.
"There's a lack of significant differentiation between Giant Eagle and Kroger's existing banners, and it happens to coincide with Meijer and Sprouts expanding, while Walmart and Aldi continue to gain share," Diana Sheehan, founder and lead advisor at PDG Insights, told me via email.

Sheehan's comments highlight the core challenge of this deal: in recent years, Giant Eagle has faced intense competition from big-box retailers and other discounters. A few years ago, it even lost the top spot in its home market to Walmart before quickly reclaiming it. For this deal to deliver full value, Kroger will need to improve Giant Eagle's market performance while also working to boost its own results.
Neil Saunders, managing director at GlobalData, noted that all this means a fairly heavy to-do list lies ahead for Kroger and its new CEO.
"For Kroger to make this deal a success, it must absorb a new business unit while fixing its own core operations," he wrote in emailed comments. "It also needs to fully leverage Giant Eagle's assets through membership programs, media networks, and other incremental revenue streams."
Despite the challenges, I don't see this as a losing deal. As Kroger seeks to improve efficiency and cut costs, there's clear value in expanding economies of scale through acquisitions. And Giant Eagle is a respected company, known for innovations in loyalty programs and digital operations. As the two companies sharpen their edge together against rivals like Walmart, it does have capabilities that complement Kroger's business.
But I'm also not convinced this is a home run, or even a solid hit. Investors seem to feel the same way—Kroger's stock rose just over 3% on Wednesday.
"Clearly, this is not a transformative deal, but store overlap is relatively low (we count about 12 Giant Eagle stores within 5 miles of existing Kroger stores), and it gives Kroger entry into new territory at a reasonable price," Michael Infranco, assistant vice president at RetailStat, wrote in an email.
Honestly, I hadn't expected Kroger to make an acquisition in the near term. Foran (Kroger's CEO) has been focused on organic growth and extracting more value from the company's existing assets—especially its stores—rather than looking beyond its food empire. Still, I applaud him and the company for staying flexible and opportunistic.
Ultimately, this acquisition by Kroger is a vote of confidence in the improvement strategy taking shape under Foran's leadership. Although Giant Eagle's competitive struggles may seem like a warning sign, Kroger clearly views it as an opportunity to expand its turnaround plan.
Sam Silverstein contributed to this article.